
California voters rejected a billionaire tax measure this month, making one thing unmistakably clear: ordinary households won’t get a policy rescue this holiday season. For families already paying 21.19% interest on credit card balances (Federal Reserve, August 2026), that reality hits especially hard right now. Black Friday is eleven days away, on November 27. Store credit card sign-ups will be everywhere at checkout. Knowing what’s buried in those offers could save you hundreds of dollars in 2027.
Quick Answer
Are store credit card Black Friday offers worth it?
Store credit card Black Friday deals often advertise 0% financing, but many carry deferred interest clauses that charge the full promotional rate retroactively if you don’t pay the balance in full by the deadline. With the average credit card APR at 21.19% (Federal Reserve, August 2026), one missed payoff can cost far more than the original discount. Read on for details on what to watch before you sign.
What the California Tax Vote Actually Means for Your Wallet
California voters rejected a proposed one-time tax on billionaires, according to U.S. media projections (RTE, November 2026). The economic signal is broader than one state’s ballot. It reinforces that households navigating high-rate debt can’t count on policy-driven relief arriving before the holidays. The burden stays personal.
U.S. consumers are already carrying $1.37 trillion in revolving debt (Federal Reserve, September 2026). The national unemployment rate sits at 4.1% (Bureau of Labor Statistics, October 2026), meaning most people have jobs but many budgets are already stretched. When retailers push store credit card Black Friday sign-ups this month, they’re doing it into a consumer environment where carrying a balance for even a few months gets expensive fast.
Where American Households Stand Right Now
The U.S. median household income is $74,580 (U.S. Census Bureau, 2023 national median). That income has to absorb elevated grocery prices, elevated gas prices, and credit card interest running at 21.19% on average (Federal Reserve, August 2026). The Consumer Price Index reached 337.511 in October 2026 (Bureau of Labor Statistics), reflecting persistent cost pressure across the economy.
Store cards typically carry rates well above that 21.19% average. Many retail-branded cards price their APRs in the 28% to 32% range. For households relying on the discount to justify the purchase, those rates can erase the savings within a single billing cycle if the balance isn’t cleared. If you’ve been researching broader options, resources on best debt relief programs florida 2026 and debt consolidation vs debt settlement texas show how people in similar situations are evaluating their paths forward.
What Should You Read Before Signing a Store Card at Checkout?
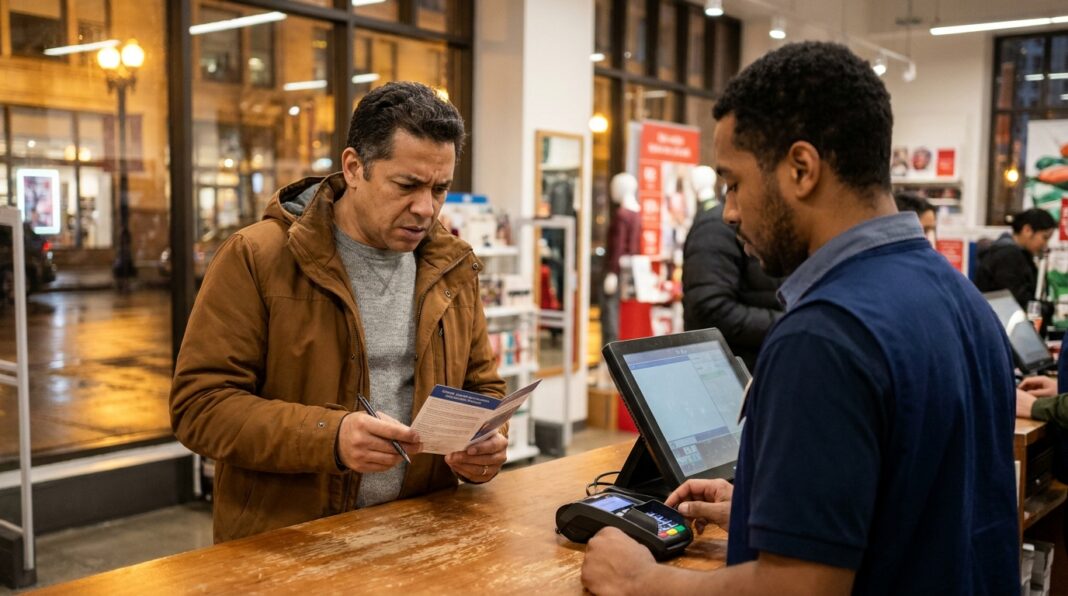
Retailers design the checkout experience for speed. You’re handed a tablet, told you’ll save 20% today, and asked to sign. Here are the terms that actually determine whether this deal works for you.
Deferred interest vs. true 0% APR. These are not the same thing. A true 0% promotional APR means no interest accrues during the promotional window. Deferred interest means interest accrues the entire time but is waived only if you pay the full balance by the deadline. Miss that deadline by a single day, and the full accrued amount gets added to your balance retroactively. Many store cards use the deferred interest structure, not true 0% APR. Read the fine print for the phrase “deferred interest” before you sign.
The standard APR after the promotional period. Whatever the promotional offer says, the standard rate is what matters most. If you don’t pay the balance in full before the period ends, that standard rate applies immediately. Store card APRs are typically higher than general-purpose credit cards. Confirm the standard rate before the cashier moves on.
The minimum payment trap. Say you charge $1,200 to a store card at a 29% APR and make only minimum payments. If that card carries deferred interest and the promotional period is 12 months, minimum payments alone almost certainly won’t clear the balance. You’d owe interest on the original $1,200 from day one. The minimum payment schedule is designed to extend your payoff timeline, not shorten it.
Credit inquiry impact. Applying for a store card triggers a hard inquiry on your credit report. One inquiry has a small, temporary effect. But signing up for two or three cards across Black Friday weekend can compound that impact at the exact moment you may need your credit profile in the best shape, whether for a consolidation loan, an auto loan, or a lease renewal. Those considering consolidation options in the new year can find guidance on debt consolidation houston tx as a starting point.
How Families Are Getting Ahead of Holiday Debt
The math on existing high-rate balances is straightforward. The average 24-month personal loan rate is 11.9% (Federal Reserve, August 2026), compared to the 21.19% average credit card rate. Say you’re carrying $6,000 in existing credit card debt at 21.19%. Over 24 months making fixed payments, you’d pay roughly $1,430 in interest. At 11.9%, that same balance over 24 months costs about $750 in interest. That’s a meaningful difference before you add a single holiday purchase.
Consolidating existing balances before the holidays puts you in a stronger position. It lowers the monthly interest cost, simplifies your payment, and makes it easier to track exactly how much headroom you have for holiday spending without accruing new high-rate debt. Debthunch matches people with live debt solution providers, including debt settlement programs, debt resolution, debt consolidation programs and debt consolidation loans.
Debt settlement is a separate path, and it’s worth understanding the difference. Settlement involves negotiating a payoff for less than the full amount owed. That can make sense for people with significant unsecured debt and genuine financial hardship. But the tradeoffs are real: settlement damages credit scores, settlement companies charge fees, creditors aren’t required to agree, collection calls and potential lawsuits can continue during a program, and forgiven debt may be taxable income. If a creditor settles and cancels the remaining balance, they may issue IRS Form 1099-C. Consolidation is usually the better fit for people who have income and are looking to reduce interest costs rather than reduce principal.
Steps to Take Before the Black Friday Pressure Gets to You
- Audit your current balances and rates now, before November 27. Write down every card balance, its APR, and its minimum payment. That number gives you a baseline. You can’t make a smart decision at the checkout counter without knowing what you’re already carrying.
- Decide in advance which purchases you’ll finance and for how long. If you plan to use a store card, calculate whether you can pay the full balance before the promotional period ends, using scheduled payments, not minimum payments. If the math doesn’t work, the offer isn’t worth taking.
- If existing balances are already a problem, explore consolidation options before the holiday spending season adds to them. Starting the new year with high-rate balances from multiple cards is the most common way holiday spending becomes a year-long financial drag. Visiting Debthunch to see what debt solution providers are available is a reasonable first step, with no commitment required to explore.
Store card balances piling up? The holiday season moves fast, but the debt it creates moves slowly. Explore options before Black Friday, November 27, while you still have time to make a deliberate choice. Debthunch matches people with live debt solution providers across consolidation, resolution, and settlement programs.
Frequently Asked Questions
What is deferred interest on a store credit card Black Friday offer?
Deferred interest means interest accrues on your balance from day one but is waived only if you pay the full amount by the promotional deadline. Miss that date and the full accumulated interest gets added to your balance immediately. It differs from a true 0% APR, where no interest accrues during the promotional window.
How does a store card APR compare to a personal loan rate?
Store card APRs are typically well above the national average credit card rate of 21.19% (Federal Reserve, August 2026). The average 24-month personal loan rate is 11.9% (Federal Reserve, August 2026). Carrying a balance on a store card rather than a personal loan adds significant interest costs over time.
Who should consider debt consolidation instead of opening a new store card?
Anyone already carrying revolving balances at high interest rates is a candidate for consolidation before adding new holiday debt. Consolidation makes the most sense for people with steady income who want to reduce their interest rate and simplify payments. Those with severe hardship may need to evaluate settlement separately.
What are the risks of signing up for a store credit card at checkout?
Risks include a hard credit inquiry, deferred interest terms that charge retroactive interest if the balance isn’t cleared on time, a high standard APR after the promotional period ends, and the temptation to overspend because a large credit line is suddenly available. Each of these can cost more than the initial checkout discount.
Where can I explore options if my existing credit card balances are already high?
Debthunch matches people with live debt solution providers, including debt consolidation loans, debt consolidation programs, debt resolution, and debt settlement programs. Reviewing options before adding holiday spending is the most effective time, since consolidation applications consider your existing balance and credit profile together.
This article was reviewed for accuracy and produced with data from the following authoritative government sources:
- Federal Reserve Economic Data (FRED) — Interest rate and consumer debt data. fred.stlouisfed.org
- U.S. Census Bureau — Median household income data. census.gov
- Bureau of Labor Statistics (BLS) — Employment and CPI data. bls.gov
This content is for informational purposes only and does not constitute financial advice. Consult a qualified financial advisor before making debt-related decisions.